Capital allocation is a corporate strategy discipline, not investing advice
This article is about how a company deploys its own free cash flow. It is written for the CEO, CFO, or board of a large corporate deciding across the full ladder of capital uses: reinvestment in the core, M&A, debt reduction, dividends, buybacks, and strategic optionality. It is not investment advice, and it is not about personal investing. Nothing here tells an individual what to buy; the subject is the corporate discipline of turning operating cash into long-run intrinsic value per share.
That discipline is the CEO's most consequential job and often the least trained for. Warren Buffett put the problem plainly: once executives become CEOs, they must make capital allocation decisions, a critical job that they may have never tackled and that is not easily mastered.[1] The skills that get someone to the corner office, running a P&L, building a product, closing a customer, are not the same skills that govern how capital is raised, managed, and disbursed. Yet the stakes compound: every dollar of free cash flow is either compounded inside the business or handed back, and the difference between a disciplined allocator and an undisciplined one shows up in the share price over a decade.
The evidence suggests most companies allocate far worse than they could. Researchers cited by Morgan Stanley's Counterpoint Global measured how much capital firms reallocate between business units and found an optimal degree of reallocation, but only 38 of 5,760 firm-year observations, less than 1 percent, were above that threshold.[1] The pattern is consistent with status quo bias: management teams keep funding last year's allocation even when preferable alternatives exist, the budget inertia that a strategic resource allocation discipline is designed to break.[1]
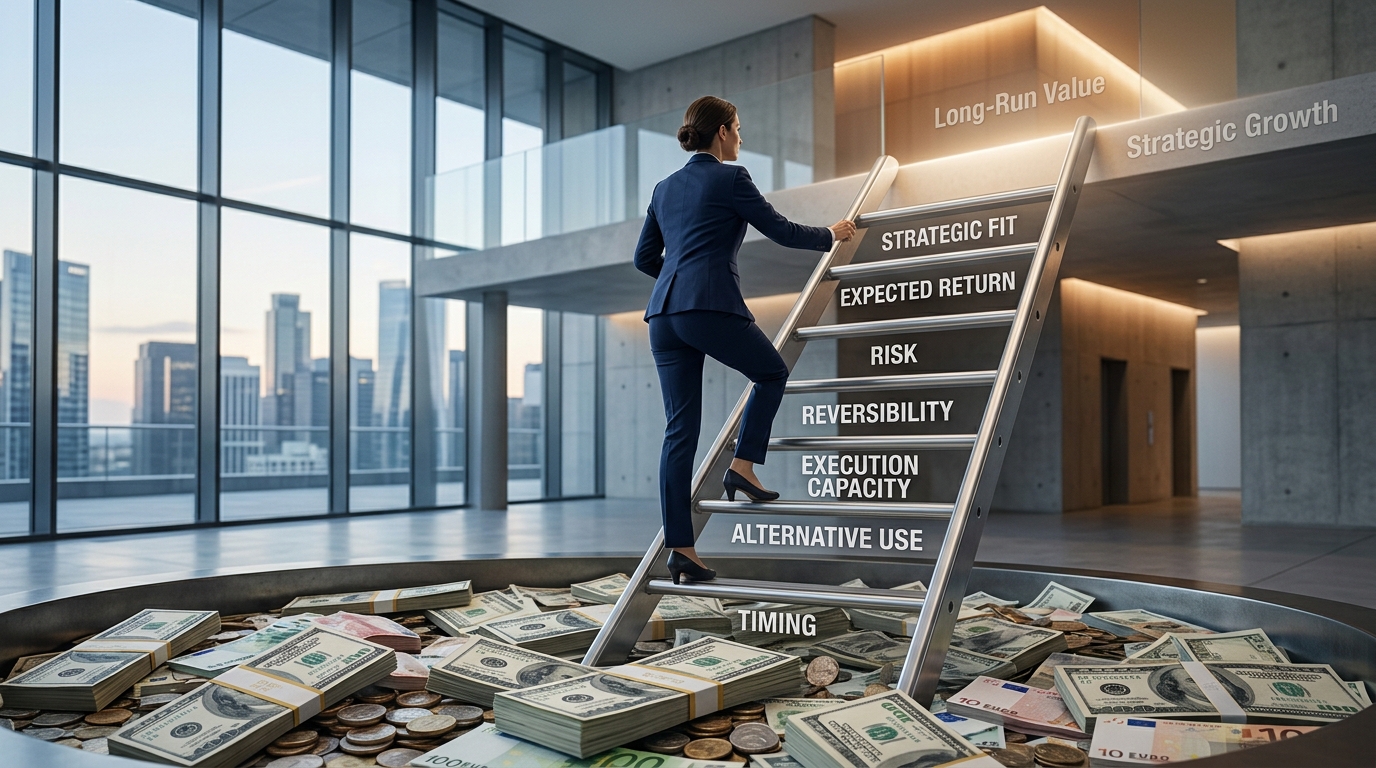
The fix is not a cleverer spreadsheet. It is a repeatable framework that forces every competing use of cash through the same explicit tests, so the decision is a ranking against alternatives rather than a habit. We call it THE CAPITAL ALLOCATION LADDER. Each rung is a question every proposal must answer:
- Strategic fit: does this use strengthen a business we understand and want to own?
- Expected return: what cash-on-cash return can we credibly expect, against what evidence?
- Risk: what has to be true for this to work, and how wrong can we be?
- Reversibility: if it fails, how costly and slow is the exit?
- Capacity to execute: do we actually have the management bandwidth and skills to deliver it?
- Alternative use: what is the specific next-best use of this same dollar?
- Timing: is this the right moment, or should we hold the option and act later?
The sections that follow walk the ladder rung by rung across each major use of free cash flow, then show how to turn the framework into a governance cadence the board can actually run.
Reinvestment in the core and the hurdle-rate question
When returns clear a properly set hurdle, reinvestment in the core should almost always be the first claim on free cash flow. No acquisition premium, no integration risk, no signalling complication: the company already owns the assets, knows the customers, and controls the outcome. The empirical case is strong. BCG's capital allocation database, covering more than 10,000 listed firms, found that outperformers, the companies in the top third of stock market valuation relative to their peers, invested approximately 50 percent more in capex than their peers and achieved approximately 55 percent higher returns on assets, along with roughly 65 percent higher sales growth.[2]
The failure modes are predictable. BCG names two traps. The egalitarian trap gives every business unit its fair capex share irrespective of potential, which quietly starves the best businesses. The maturing-business trap keeps capex flowing into a business that no longer earns its cost of capital, because nobody wants to admit the growth era is over.[2] Both traps are allocation by habit, not by return, and both are exactly what the ladder's expected-return and alternative-use rungs are designed to expose.
Setting the hurdle rate
The reinvestment test is only as good as the hurdle it clears. The 2026 AFP Cost of Capital Survey found that 62 percent of organizations use their calculated cost of capital as the standard hurdle rate, while 38 percent set a hurdle rate above the cost of capital to account for additional risk such as execution risk or market uncertainty.[3]
Why is WACC alone the wrong answer? Because it is a company average. It ignores project-specific risk, so a speculative product launch and a warehouse upgrade get discounted at the same rate. It ignores capital rationing, where the real question is not whether a project beats the average cost of money but whether it beats the projects it displaces. And it ignores the option value of waiting: sometimes the right move is to defer spending until uncertainty resolves. Practitioners in the AFP survey converge on the same best practice: keep the hurdle rate stable and reflect risk in explicit cash-flow scenarios instead. As one finance leader put it, adjusting cash flows rather than the discount rate makes the sources of risk explicit and keeps the cost of capital consistent, which improves comparability across projects.[3]
| Ladder rung | What to test for reinvestment in the core |
|---|---|
| Strategic fit | Does the investment strengthen an existing business with durable advantage? |
| Expected return | Does the project's scenario-weighted return clear the hurdle rate? |
| Risk | Are the critical assumptions explicit, with break-even and downside scenarios? |
| Reversibility | Capex in the core is usually partially recoverable through utilization or resale |
| Capacity to execute | Does the operating team have bandwidth, or does this crowd out current priorities? |
| Alternative use | Which project or payout does this dollar displace if funded? |
| Timing | Is demand certain enough now, or does waiting preserve a cheaper option? |
M&A: three deal archetypes and why most deals create no value
M&A sits higher on the ladder than reinvestment because it adds a premium, an integration risk, and a counterparty to every return. The base rates are sobering. Companies worldwide conclude roughly 5,000 acquisitions a year for a total deal value of around $2 trillion, yet most of that spend fails its buyers: Lev and Gu's statistical analysis of 40,000 acquisitions over 40 years found that 70 to 75 percent of deals fail their stated objectives of enhancing post-acquisition sales growth, cost savings, or maintaining the buyer's share price, with conglomerate and large-target deals failing most often.[4]
Most corporate deals fall into one of three archetypes, and the ladder treats each differently:
- Scale or cost-synergy absorption: buying a competitor or adjacent asset to consolidate volume and strip out duplicated cost. The synergy case is concrete, which is why these deals fail least often, but the premium paid can still consume the entire saving.
- Capability or market extension: buying a product, technology, or geographic footprint the buyer lacks. The strategic fit rung does the heavy lifting here, because the buyer must honestly assess whether it can absorb a capability it does not already have.
- Transformative growth-platform deals: the big bet that changes the company. These carry the widest dispersion of outcomes and the highest failure rates, particularly when the target is large or unrelated to the core.
The failure modes are consistent across the research: overpaying in competitive processes, buying a strategically misfit target, failing to integrate it properly, and incentive structures that reward deal completion over deal success. Lev and Gu note that many CEOs earn acquisition bonuses simply for completing a deal, that executive pay rises with company size, and that serial acquirers enjoy longer tenure, so the emphasis lands on completion rather than success.[4] The same authors document that the alternatives, internal development of capacity, partnerships, and joint ventures, often earn higher returns than acquisitions, and conclude that acquisitions should be the last resort, not the first option.[4] On the ladder, M&A must beat not only the hurdle rate but the build-and-partner path on strategic fit, risk, and reversibility before it earns the capital.
Debt reduction and strategic optionality: when balance-sheet strength beats returns
Not every dollar should chase the highest expected return. Two uses of cash derive their value from what they make possible rather than from their direct yield: paying down debt and holding strategic cash.
Leverage optionality is the first. If debt levels put covenant headroom, refinancing access, or investment capacity at risk in a downturn, deleveraging preserves the ability to act when assets are cheap. That option, the capacity to buy counter-cyclically while competitors are constrained, can be worth more than the spread between a project's return and the cost of debt. A company that deleverages into strength keeps its balance sheet as dry powder; a company that maximizes leverage to fund marginal projects loses the option precisely when it is most valuable. The ladder's reversibility and timing rungs are where this trade-off gets decided explicitly.
Strategic optionality is the second: holding cash for capabilities you cannot yet name. This is not sloppiness; it is a deliberate position, sized against the cost of carrying it. The discipline is to state what the cash is for, the downturn it is meant to survive, the acquisition it is meant to enable, the capability investment it is meant to fund, and to review that sizing annually like any other allocation.
Capital structure is itself an allocation decision, not a side constraint. Morgan Stanley's Counterpoint Global analysis tracks the US corporate debt-to-total-capital ratio back to 1970 for companies outside the financial sector, treating how a firm finances its operations as a decision that belongs on the same list as investment and payouts.[1] For a CFO office, the implication is that holding balance-sheet capacity is a competitive norm, not a timidity signal, and that the burden of proof should sit on proposals that would spend it.
| Signal | What it suggests on the ladder |
|---|---|
| Covenant headroom tightening or refinancing wall ahead | Debt reduction outranks marginal projects regardless of spread |
| Downturn expected to create cheap assets | Preserve deleveraging and cash as an option; the timing rung dominates |
| No credible near-term use for excess cash | Size strategic optionality explicitly and review it annually |
| Strong balance sheet, weak project pipeline | Returning capital may beat forcing marginal reinvestment |
Dividends and buybacks: returning capital without destroying it
When the business has taken all projects that clear the hurdle, returning capital is not a failure of ambition; it is the discipline that keeps the ladder honest. But the two return channels behave very differently, and each has a distinct failure mode.
Dividends are a signalling and shareholder-base instrument. Management teams commonly treat them as sacrosanct while viewing buybacks as discretionary, and the volatility data bear this out: Morgan Stanley's Counterpoint Global analysis found that share buybacks are far more volatile than dividends, even though the two are arguably interchangeable as payout mechanisms.[1] A dividend commitment therefore designs the shareholder base: it attracts income-oriented holders and forces management to defend the payout through the cycle. The failure mode is rigidity, maintaining a dividend the business can no longer afford because cutting it is read as distress.
Buybacks are less mechanical than they look, because the price paid decides whether value is created or destroyed. Research summarized by Alex Edmans found that firms that buy back stock subsequently outperform their peers by 12.1 percent over the next four years on average, evidence that repurchases made at attractive prices add value for remaining holders.[5] The same logic cuts the other way: buying above intrinsic value transfers wealth from the company to selling shareholders and destroys value for everyone who stays. The failure mode is mechanical execution, running a repurchase program on a schedule rather than against a valuation test.
The buy-high pattern is documented. NACD's guidance for boards notes that S&P 1500 companies spent significant capital buying back stock between 2006 and 2008, only to pull back between 2009 and 2011, when valuations and share prices were much more attractive. The timing, NACD concludes, was terrible.[6] A board that applies the ladder's timing and expected-return rungs to buybacks, asking what price per share makes the repurchase accretive to intrinsic value per share, avoids exactly this inversion.
Why balanced allocation is incoherent: opportunity cost and the next-best use
The most common allocation posture in corporate boardrooms is also the least defensible: a bit of everything. Some capex, some M&A pipeline, a steady dividend, a buyback authorization, a cushion of cash. It feels prudent, and it is usually incoherent, because every dollar has exactly one next-best use. Allocation is a ranking problem, not a splitting problem. A balanced spreadsheet is not a strategy; it is a portfolio of unranked decisions that quietly funds mediocre projects alongside good ones, and the mediocre projects are the ones that never get re-examined.
NACD's board guidance makes the discipline concrete: every capital deployment decision should be subject to a comprehensive analysis of expected cash-on-cash returns, followed by a comparison against the returns from alternative forms of capital deployment, including taking no action. Some of the best capital allocation decisions, NACD notes, are those to say no.[6] Doing nothing is a genuine alternative with a measurable return: the cash stays available for the next proposal, the balance sheet keeps its optionality, and the dividend capacity is preserved.
This is what the alternative-use rung of THE CAPITAL ALLOCATION LADDER operationalizes, and it is the same logic a strategic options framework applies to any major choice: a proposal is never simply good. It is better than the specific next-best use it displaces, and the burden is on the sponsor to name that alternative and show the comparison. A project returning 14 percent is not attractive if the displaced alternative returns 18 percent; a buyback at 20 times earnings is not shareholder-friendly if the core business can reinvest at 25 percent returns. Ranking every use of free cash flow on one list, including debt reduction, payouts, and holding cash, is what converts the ladder from an evaluation checklist into an actual allocation decision.
- Rank, don't split: order all competing uses of free cash flow by expected value created, and fund from the top until the marginal use no longer clears.
- Include the null option: doing nothing, holding cash, or paying down debt are alternatives with real returns and belong on the same ranked list.
- Name the displaced use: every approved proposal should state which next-best use it beat, and by how much.
- Revisit the losers: a proposal that lost this quarter may win the next, which is why the ranking, not the decision, is the durable artifact.
Governance cadence: the annual capital plan and quarterly re-look
A framework that runs once is an analysis. A framework that runs on a cadence is a capability. The governance rhythm that makes THE CAPITAL ALLOCATION LADDER repeatable has two beats.
The first is the annual capital plan. Once a year, the CFO office ranks every use of free cash flow on a single list: core reinvestment, M&A candidates, debt reduction, dividends, buybacks, and strategic optionality, each scored against the seven rungs. The output is not a budget but a ranking, with the displaced alternative named for every approved item. The second beat is the quarterly re-look. Rates move, valuations move, and project assumptions move; a quarterly session re-scores the top of the ranking and asks which decisions the new facts change. A buyback that failed the valuation test in March may pass it in September; an acquisition thesis built on a financing assumption may not survive the quarter.
Board practice, per NACD and BCG, adds three disciplines to the cadence. First, compare realized returns with original projections, asking which deployments beat or missed their business cases and why, so the process learns from success and failure.[6] Second, run premortems and explicit scoring criteria for major proposals, the kind of management consulting frameworks that earn their keep in the boardroom: BCG recommends imagining that the investment has failed terribly and asking everyone to find the reasons, which shifts the discussion from confirming potential to uncovering hidden risks.[2] Third, never deploy capital from a position of weakness: NACD warns that a firm should not undertake acquisitions, repurchase shares, or approve a large capital program to cover up a potential earnings-per-share miss, because letting returns become subservient to a broader strategic objective tends to destroy shareholder value.[6]
Running this cadence well is a workload problem as much as an analytical one: the annual plan and every quarterly re-look require the same documents to be re-read, re-scored, and re-traced to source. This is where an AI-native strategy platform like Decisity earns its place in the CFO office. It structures capital-allocation trade-offs on the company's own financial documents, scoring proposals against explicit criteria and keeping every number clickable to its source, so the board sees a ranking it can audit rather than a deck it must trust. For teams managing capital across a portfolio of businesses, Decisity Portfolio Management applies the same source-traceable approach to assessing assets and allocating capital. The ladder tells you what to ask; the cadence makes the organization answer it every year, every quarter, with evidence attached.
Related: Decisity for portfolio management.